How does the debt snowball tracker work?
- Type each debt: a name, the balance, the APR (the yearly interest rate) and the minimum payment.
- Type the extra you can add each month, and pick snowball or avalanche.
- Download the plan: a PDF to print (page one is the plan, the pages after it are the month-by-month tracker) or the same schedule as a CSV for your spreadsheet. Two more downloads sit beside them: the blank worksheet for the pen-and-paper route, and the same worksheet pre-filled with your plan.
The order rules are stated, not implied: snowball clears the smallest balance first (ties go to the higher rate), avalanche clears the highest rate first (ties go to the smaller balance). Interest is charged monthly at APR ÷ 12 before the payment lands.
What does the math do each month?
| Step | What happens |
|---|---|
| 1 | Interest is added to every remaining balance |
| 2 | Every debt pays its minimum (never more than the balance left) |
| 3 | All the leftover money, your extra plus the freed minimums of cleared debts, lands on the first debt in the order |
| 4 | If that debt clears mid-month, the rest of the pile rolls onto the next one the same month |
Because the freed minimum of every cleared debt joins the pile, the payment aimed at the target grows each time a debt dies. The printed tracker names the target each month, so the plan on paper and the plan in the bank stay the same thing.
What’s on the printed worksheet?
Page one is the plan: your debts in payoff order, each with balance, rate, minimum and the month it clears, then the totals (owed today, total interest, total paid, debt-free month). The tracker pages carry one row per month: the month, the debt the pile lands on, the payment, a tick box, and the debts that clear that month. To state the debt-free date the way a letter or a contract needs it, the date calculator gives the same span in days, weeks and working days.
Print at 100 percent on A4 or US Letter. One page per month of the plan is not needed: the tracker fits 27 months a page.
Both worksheet kinds print from the page: the blank sheet gives you twelve debt rows to write out, a payoff order column to number smallest balance first, and a 27-month payment tick grid (print the page again for a longer plan); the worksheet with my debts is the same layout pre-filled with your debts already in snowball order, your payoff months, and the payment each month needs, computed by the same math as the tracker.
What the tool refuses to do
If the minimums do not cover the monthly interest, no payoff date exists: the balances grow forever. The tool says so in plain words and refuses to print a plan with a fake end date. That refusal is the honest answer; raising the extra payment or renegotiating a minimum is the real one.
The tool also does not advise. Snowball versus avalanche is a real trade: cheapest total against earliest win. Switch the Method box to see the other order’s months and total interest for your debts; the choice stays with you. This sheet does the math; it is not financial advice.
Why both a printable and a spreadsheet?
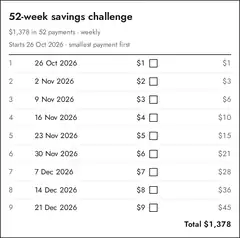
The blank worksheets on printable sites leave the arithmetic to you, so this page carries both kinds: a blank sheet for the pen-first route, and the computed plan that does the math for you. This tool does the math and hands you the forms from the same typed-in numbers: a computed, dated plan you print and tick off with a pen each month, and the same schedule as a CSV file that opens in Excel, Google Sheets, Numbers or LibreOffice. Its rows are one per month: the payment each debt gets, the pile payment landing on the debt being cleared, and the balance left after it. The arithmetic is ours either way; the spreadsheet app is optional, a place to keep the plan rather than to do the math. There is no signup, and it works with up to 12 debts. When the debts are gone, the 52-week savings challenge sheet is the natural next thing.
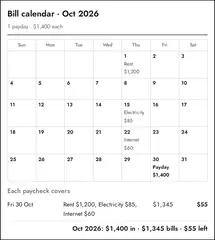
While you pay the plan down, the bill calendar by paycheck keeps the months themselves straight: every bill on its due date, each paycheck with the bills it covers.
Questions
Is this debt snowball worksheet really free?
Yes: no email, no account, no watermark. The plan prints from your own device, and the CSV export is free too. Some big personal-finance sites hold their spreadsheet back behind an email gate or a paid tier above ten debts, and Etsy sellers charge a few dollars for blank trackers (checked 6 October 2026).
Is there a blank worksheet I can fill in by hand?
Yes. One button downloads the blank sheet: debt rows for the name, balance, rate and minimum of every debt, a payoff order column to number smallest balance first, and a month-by-month payment tick grid. The button next to it prints the same worksheet pre-filled with your debts and the computed plan.
What is the difference between snowball and avalanche?
Same payments, different order. Snowball pays the smallest balance first, so a debt disappears quickly and the motivation arrives early. Avalanche pays the highest interest rate first, which is the mathematically cheaper order. This tool does both in one click and shows you each debt's payoff month and the total interest for the order you chose.
How much interest does the snowball save?
That depends on your debts; this tool computes it. On one worked example, a $420 store card at 0%, a $1,800 credit card at 19.9% and a $2,600 loan at 9.4% with $60 extra a month, the totals come out $723 of interest in snowball order and $670 in avalanche order: paying the 19.9% card first saves $53 here, and both orders finish on the same month. Where the smallest balance carries the highest rate, the two orders cost the same. Type your debts and flip the Method box to see your two totals.
How does the snowball roll forward?
Every debt keeps paying its minimum. When a debt clears, the money that was going to it, plus any extra you typed, rolls onto the next debt in the order, in the same month. That growing pile is the snowball, and the printed tracker shows it landing.
Is my financial information uploaded anywhere?
No. Debt numbers are among the most private data there is, which is why this tool has no server at all: the plan is computed in your browser, the PDF and the CSV file are built there, and closing the tab erases everything. You can watch the network tab while you use it: no request carries your numbers.
Does the plan account for interest?
Yes: interest accrues monthly at APR divided by 12 before each payment, so payoff months and the total interest include it. A 0% APR is fine too; promotional-rate debts are common in snowball plans.
Is this financial advice?
No. The sheet does arithmetic (payoff order, months, interest totals) and prints it. It does not tell you whether snowballing is right for your situation, and it says so on the printout. For decisions, talk to a qualified adviser or a nonprofit credit counselling service.